Homeownership: Why Owning a Home Matters More Than You Think
For many Nigerians, owning a home is a dream that stays in the background for years. Most people start thinking about it when they get married, when children arrive, when their careers stabilise, or perhaps when rent increases. Many of us want to own a home, but the path to achieving this goal is often unclear. That distinction matters.
Homeownership is often seen as a matter of having enough money to buy a house. However, the process is more complex and, in some respects, more encouraging. Income, house prices, and interest rates are important, but awareness is equally critical and often overlooked. Many Nigerians may not pursue homeownership because they believe it is unattainable, often without fully understanding their available options. Perhaps the first step toward homeownership isn't finding a house; it's understanding the process.
A home is more than four walls, a roof and an address. A home provides stability and belonging. It offers families a place to put down roots and plan with confidence. It also allows individuals to personalise their environment to reflect their lives and aspirations. Long-term renters may find ongoing uncertainty exhausting. Rents can rise, landlords may change plans, and families might need to move if a property is sold or becomes unaffordable. While homeownership does not remove all uncertainties, it offers greater control over where we live.
For many Nigerians, owning a home is more than a financial transaction; it represents stability, security, and permanence. It also has an important financial dimension. A well-located property can become a valuable household asset, appreciating as infrastructure and communities develop. This ownership stake can contribute to a family's long-term wealth. A home should be seen not only as a place to live, but also as part of a broader financial plan.
That is not to say renting is necessarily a bad financial decision. In fact, for many people, it is the appropriate choice at a particular stage of life. Those starting their careers may need the flexibility of renting. Individuals unsure of where to settle may avoid property commitments, while others may not yet have the financial means to buy. The important question, then, is not whether renting is good or bad. The more important question is this: If you expect to spend on housing for the next ten, fifteen, or twenty years, have you considered what ownership could offer you?
Rent payments secure temporary occupancy, while home purchase payments help build ownership in an asset. Although both involve regular payments, the long-term financial outcomes differ significantly. Anyone expecting to pay for accommodation long-term should understand the alternatives.
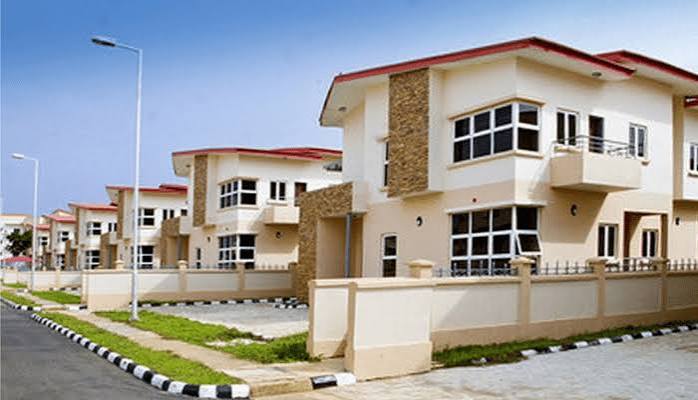
A major challenge for aspiring homeowners in Nigeria is not just limited housing finance, but a lack of awareness about how it works. The term "mortgage" can seem intimidating. Many associate it with complex procedures, high income requirements, significant interest costs, and exclusivity for the wealthy. These concerns are valid. Buying a home is a major financial commitment, and mortgage financing carries responsibilities. However, assumptions should not discourage people from seeking information.
Is a mortgage only for high-income earners? How much equity is needed? What income level is required? How are monthly repayments determined? What documents are necessary? What if circumstances change? Which properties qualify? These questions aren't reserved for property experts. Every aspiring homeowner should understand these questions.
This is why awareness is essential. There is a significant difference between saying, "I cannot afford a house," and asking "What kind of house can I afford, and what would I need to do to own it?" The first is a conclusion. The second activates a financial plan.
Is homeownership only for the wealthy? This is one of the most common assumptions surrounding homeownership. Many people see properties listed for tens of millions of naira and assume ownership is out of reach because they lack the full amount in cash. However, the property price and the initial cash a buyer needs are not always the same. This is one of the important roles of mortgage finance.
A mortgage allows a qualified buyer to make an initial payment and finance the remaining balance over time, based on lender requirements and mortgage terms. That changes the question. Instead of asking, "Where will I find the entire purchase price?" aspiring homeowners can ask, "What can I afford? What equity contribution is required? What mortgage could I qualify for? What would my monthly repayment be?" These are much more practical questions. Once you start asking these questions, homeownership becomes a practical goal rather than just an aspiration.
What about the cost of a mortgage? Of course, mortgage financing is not free money. Interest is a high cost, and anyone considering a mortgage should understand the full financial commitment, not just the purchase price. But the calculation has another side. A mortgage spreads the cost of buying a home over time, so buyers don't need to save the full purchase price before moving in. For someone with a regular income, that distinction can be crucial. Rather than waiting as prices and costs change, a suitable mortgage lets qualified borrowers acquire a home and make structured payments over time. Admittedly, affordability is key, and a mortgage must fit your financial capacity and be approached with careful planning. Homeownership is not about borrowing as much as possible. It is about finding a sustainable way to finance a home you can truly afford.
The benefits of owning a home extend beyond the financial. For families, homeownership can provide greater stability for children, fewer disruptions from moving, and more freedom to shape your living environment. It also creates a sense of permanence that is difficult to quantify. Knowing the place you live truly belongs to you has a psychological impact. Over time, the financial benefits also grow. As you repay your mortgage, your ownership stake increases. If the property appreciates, your household may benefit from its rising value. This asset can support other financial goals, such as retirement planning or providing a foundation for the next generation. This is one reason homeownership has remained such an important aspiration for families across Nigeria. People are not just trying to leave their children a house. They are trying to leave them a foundation.
So, where do you begin? The journey to homeownership does not start with visiting a developer or applying for a mortgage. It begins with understanding your financial position. How much do you earn and spend? How much can you comfortably allocate to housing? Do you have savings for an equity contribution and related costs? Is your income stable and documented? Do you know your credit position? What type of property fits your circumstances?
These questions may not produce an immediate answer. But they offer something more valuable: clarity. This is important because homeownership shouldn't be based on emotion alone. An attractive house is appealing, but the right home meets your needs and fits your financial plan. Perhaps the most important shift is not from renting to owning. It is from assumption to awareness. Many people decide homeownership is impossible before exploring their options. Others believe they must save a large sum before considering possibilities.
The reality may be more nuanced. Homeownership can be challenging. Property prices may be high, financing costs significant, and documentation processes frustrating. However, these challenges shouldn't stop you from learning how the system works. The first question should not always be, "Can I afford a house?" Sometimes it should be: "What would I need to do to become a homeowner?" Asking this question leads to effective planning. Planning, in turn, creates new possibilities.
Owning a home is both a financial and a life decision. It affects where you live, how you plan your future, the stability you want for your family, and the assets you hope to build over time. However, before the house, the mortgage, or the keys, something else must come first: awareness.
Understand how mortgage finance works, what lenders require, what you can afford, the costs involved, and the options available to you. On the MBAN website, we will continue to explore these topics and provide practical insights into mortgages, homeownership, and housing finance in Nigeria. If homeownership is one of your long-term goals, do not leave it as a distant dream. Begin by understanding the journey. There is much more to learn, and your homeownership journey may begin with the next article you read.